
UK annuity providers have deployed £22.8bn into UK productive assets across 2024 and 2025, according to the Association of British Insurers (ABI), marking the first two-year milestone of their annuity providers £100bn pledge to channel capital into the domestic economy. Of that total, £14.8bn, representing 65% of the sum, has gone into private and unlisted assets.
Where the capital has gone under the annuity providers £100bn pledge
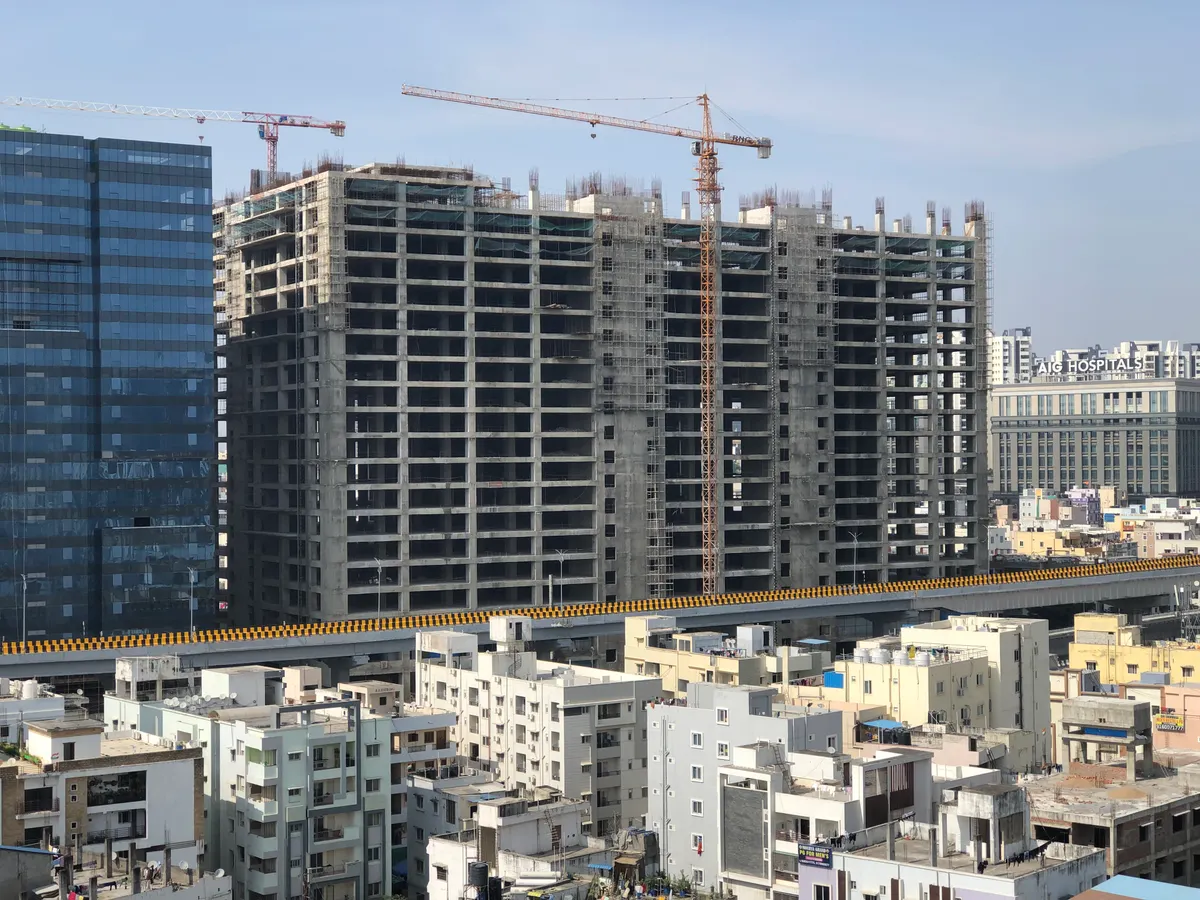
Real estate attracted the largest single allocation at £9bn, encompassing affordable and social housing, student accommodation and related property. Utilities, including energy and water supply, accounted for £5.3bn, while transport, storage and construction drew £1.8bn. Viewed by instrument rather than sector, £12.3bn was deployed through listed and private corporate bonds, with a further £6.3bn flowing into mortgages and loans.
The pace of investment is accelerating. The ABI’s update, published on 15 September, shows that £11.5bn was committed in 2025 alone, compared with the remainder in 2024. For investors seeking to understand what backs their annuity income, the breakdown matters: the bulk of the capital is financing long-duration, illiquid assets, which carry different risk characteristics from gilts or listed equities.
Hannah Gurga, director general of the ABI, said: ‘Two years into this pledge, firms have already invested almost £23bn into projects that make a real difference across the UK, from new homes and student accommodation to major water infrastructure and education facilities.’ She added that ‘maintaining a stable and predictable policy environment will be essential if firms are to continue investing at scale in the homes, infrastructure and businesses that support economic growth across the country.’
Solvency UK reforms and the risks worth watching
The £100bn commitment followed reforms to the insurance sector’s prudential framework, now known as Solvency UK, introduced during 2024 to make it easier for insurers to allocate capital to productive assets. However, the ABI cautioned that it remains too early to isolate the direct impact of those reforms on investment decisions, as firms are still adapting to the framework and building their investment pipelines. For annuitants and their advisers, that uncertainty is worth holding in mind: regulatory change of this scale takes time to translate into stable, predictable capital flows.
The capacity to invest is being supported by a growing market. The UK bulk annuity market absorbed £47.3bn of defined benefit pension liabilities in 2024 and £38.3bn in 2025, while £7.4bn of new individual annuity business was written in 2025. A larger asset base means more premium income available for long-term deployment, but it also means greater concentration in illiquid infrastructure and real estate at a time when the Solvency UK framework is still bedding in.
Lucy Rigby, economic secretary to the HM Treasury, said the data showed insurers were ‘on track to deliver on their pledge to invest £100bn in UK productive assets, like energy, housing and infrastructure projects.’ For savers holding annuities or evaluating them within a SIPP drawdown strategy, the direction of travel is clear: annuity capital is becoming a meaningful conduit for domestic infrastructure finance, with real estate and utilities at its core.
