
Credo Technology Group‘s Credo Technology valuation concern has moved to the foreground after a triple-digit share-price rally pulled forward much of the stock’s longer-term upside, prompting at least one analyst to step back from a prior Buy rating and downgrade the semiconductor maker to Hold.
The underlying business case remains intact. Credo serves hyperscalers and neoclouds through both copper and optical connectivity portfolios, and the structural shift toward higher-bandwidth data-centre infrastructure continues to work in its favour. Fiscal 2026 sales reached $1,335.12 million, with net income of $472.28 million, according to Yahoo Finance. Those are not the numbers of a company whose growth story is in doubt. The question facing investors now is how much of that story is already priced in.
The Optical Portfolio and What Fiscal 2027 Must Deliver
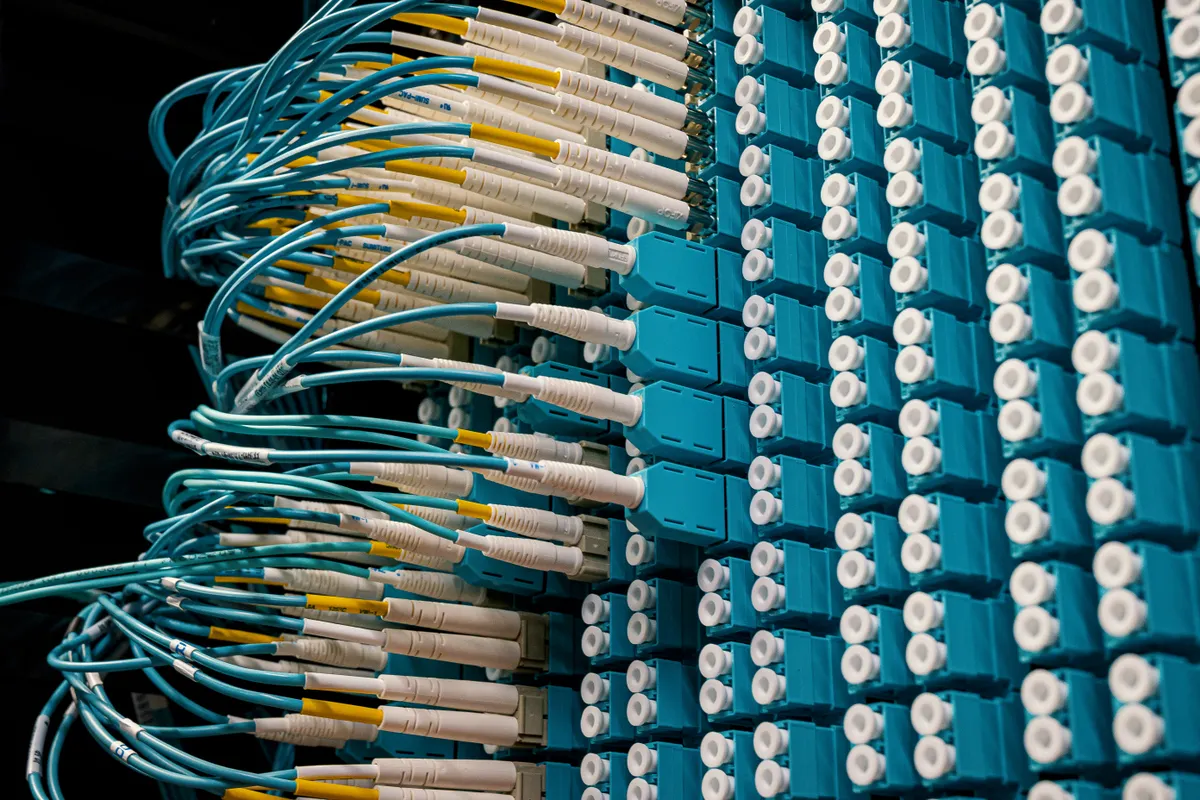
A material part of Credo’s medium-term growth thesis rests on its optical business, which is ramping with a heavier weighting in the second half of fiscal 2027. The company has stated it expects its combined portfolio of ZeroFlap Optical Transceivers, Optical DSPs, and Silicon Photonics products to generate greater than $500 million in optical revenue in fiscal 2027, according to Credo Technology Investor Relations. That target is bolstered by the acquisition of Dust Photonics, which accelerates Credo’s expansion into silicon photonics and next-generation optical connectivity.
From fiscal 2028 onwards, Credo sees additional scale-up opportunities across this expanded portfolio. For investors with a five-to-ten-year horizon, the combination of inference-driven interconnectivity demand, multi-year data-centre capital expenditure cycles, and the Dust Photonics acquisition does make for a credible long-term compounding narrative. The difficulty, as so often in growth technology, is that a credible narrative and an attractive entry point are two separate things.
Credo Technology Valuation Concern: When Good Business Meets a Full Price
The three-year price/earnings-to-growth ratio sits at 0.88x, which in isolation reads as reasonable value for the growth on offer. A PEG below 1x is often cited as a threshold of interest. Yet a single valuation multiple does not tell the full story when a stock has just delivered a triple-digit percentage gain in a compressed period. At those levels, growth expectations become embedded in the price, leaving little margin of safety if execution stumbles or if sentiment towards data-centre spending rotates.
The analyst who previously rated Credo as a Buy in March 2026, citing improved margin of safety after a prior selloff, has now set a long-term price target of $406 and identified a Buy Zone in the $150s as the level at which the risk-reward balance would become attractive again. The current price, in the view expressed, has pulled forward much of that upside potential. Momentum fatigue is cited as an additional concern: stocks that have run sharply often see painful reversals when the buying impulse fades, and the timing of such reversals is not predictable.
For UK investors holding Credo inside a self-invested personal pension or stocks-and-shares ISA, the relevant question is position sizing rather than binary in-or-out decisions. A stock with genuine multi-year structural tailwinds but a stretched near-term valuation sits uncomfortably as a new purchase yet may be worth retaining for those already holding at lower cost bases. Trimming into strength, rather than selling outright, is the kind of disciplined response that preserves exposure to the optical and AI connectivity theme without adding capital at a point of elevated risk.
Sequence-of-returns risk matters here too. For investors in or approaching drawdown, a position that falls 30-40% from its highs before recovering over three to five years represents a very different outcome from one held in a long accumulation phase. Capital preservation in the near term is not the same as abandoning the thesis entirely.
Credo’s own stated expectation of greater than $500 million in optical revenue for fiscal 2027 provides the next concrete test of whether the growth story is delivering on its promises, with the second half of that fiscal year the key period to watch.
